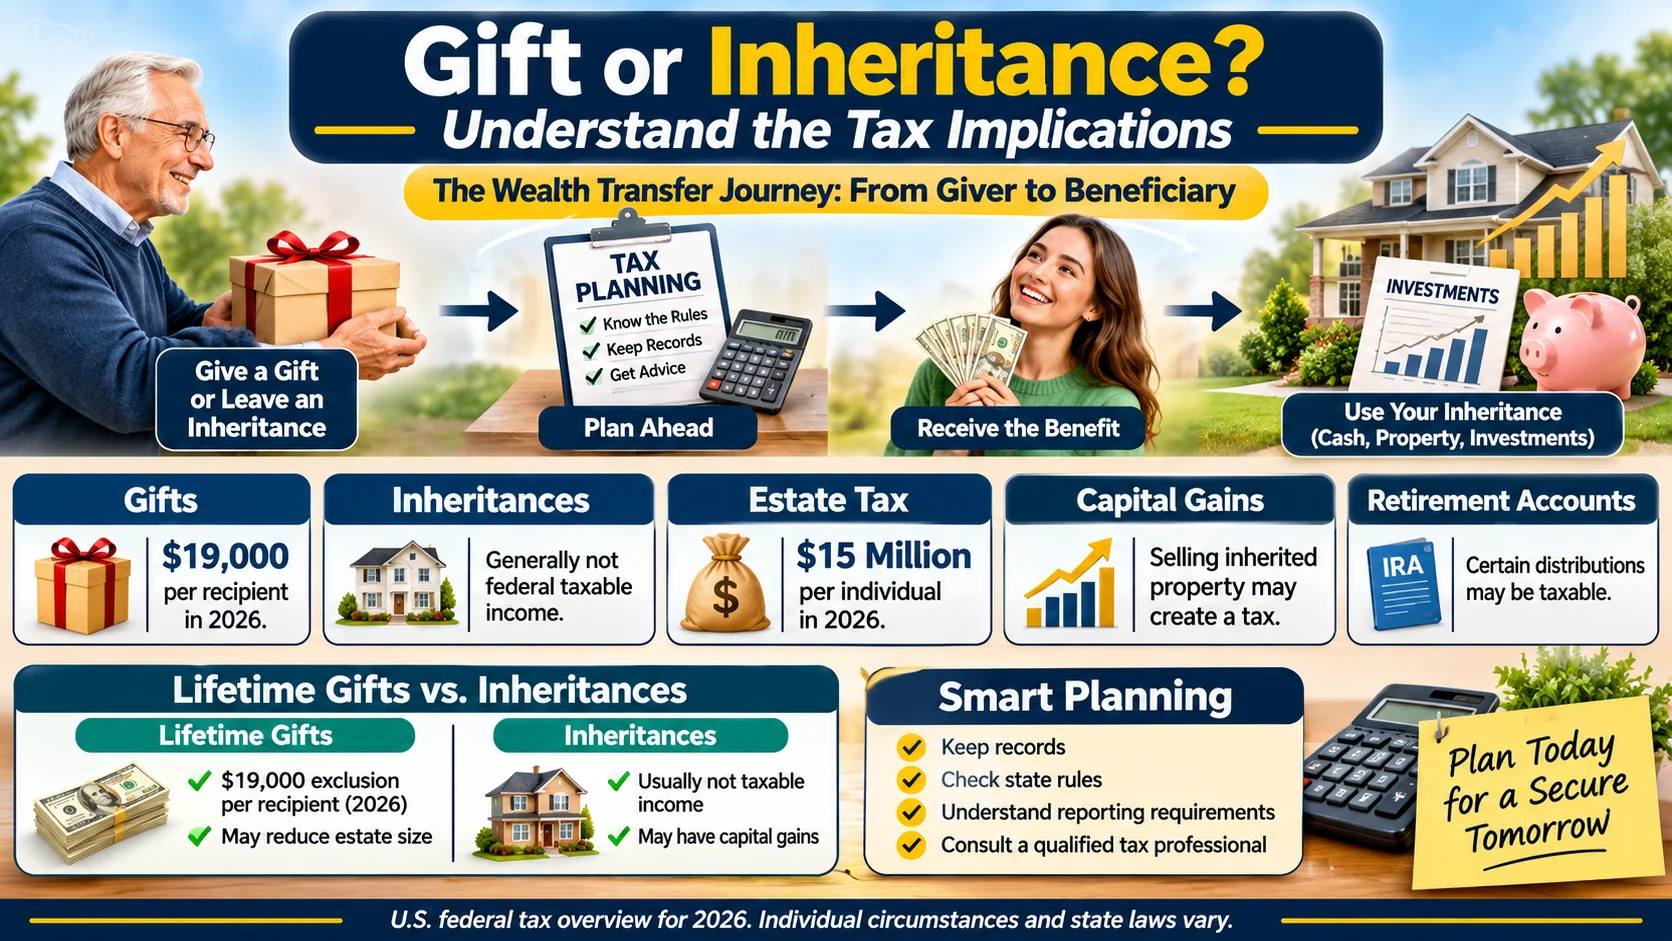
Knowing the tax implications of giving away money or an inheritance helps you avoid unexpected tax bills, understand reporting requirements, and protect the value of assets transferred to loved ones. In the United States, gifts and inheritances generally follow different federal tax rules. Therefore, understanding gift tax, estate tax, income tax, and capital gains tax can help families make informed financial decisions and plan wealth transfers more effectively.
Understanding the tax implications of giving away money or an inheritance is important because transferring wealth can affect both the person giving it and the person receiving it. Whether you plan to help your children buy a home, give money to a relative, or leave assets to your family after your death, tax rules may influence how much money ultimately reaches your loved ones.
Although giving money often feels like a simple personal decision, the tax treatment can become more complicated when the amount is substantial or the transfer involves property, investments, retirement accounts, or a large estate. For example, a cash gift may receive different treatment from an inherited house that has increased in value over several decades.
Moreover, the rules governing gifts and inheritances are not identical. In the United States, the recipient generally does not owe federal income tax simply because they receive a gift or inheritance. However, the giver may face gift tax reporting requirements, an estate may owe federal estate tax, and beneficiaries may owe taxes on certain income or gains generated by inherited assets.
By understanding these distinctions before transferring wealth, you can reduce confusion, avoid preventable mistakes, and make better decisions for your family’s financial future. This guide explains the main tax considerations, practical examples, common errors, and planning strategies to help you approach gifts and inheritances with greater confidence.
Why Is It Important to Know the Tax Implications of Giving Away Money or an Inheritance?
Knowing the tax implications matters because a financial gift or inheritance can involve more than the amount transferred. The timing of a gift, the type of asset, the value of an estate, and the recipient’s future use of the property may all affect the overall tax outcome.
Here are the main reasons to understand these rules before making a transfer.
Avoid Unexpected Tax Bills
First, understanding the applicable rules helps you identify potential taxes before transferring money or property. Although many ordinary gifts and inheritances do not create an immediate federal income tax bill for the recipient, other tax obligations may arise.
For instance, a large estate may be subject to federal estate tax if its taxable value exceeds the applicable exemption. Similarly, selling inherited investments or property may result in capital gains tax.
Consequently, planning ahead can help families prepare for possible liabilities instead of facing unexpected expenses later.
Understand Who Is Responsible for Paying Tax
Another important reason is to determine whether the giver, recipient, estate, or another party has a tax responsibility.
In the United States, the donor is generally responsible for federal gift tax, if any is due. Meanwhile, the estate generally handles any federal estate tax owed before distributing the remaining assets. Beneficiaries may also have tax obligations when they receive income from inherited retirement accounts or sell inherited property.
Therefore, understanding who is responsible can prevent misunderstandings and help everyone prepare the necessary documents.
Protect the Value of Your Wealth
Tax planning can also help you preserve more of the wealth you intend to share.
For example, a person considering a large cash gift, a transfer of investment shares, or an inheritance involving real estate should examine the tax consequences of each option. Different assets can have different tax treatments, so transferring them without understanding the rules may lead to avoidable costs.
However, the best strategy depends on the family’s circumstances, the assets involved, and the applicable laws. A qualified tax professional can help compare options before you make an irreversible decision.
Make Better Long-Term Financial Decisions
Finally, understanding gift and inheritance taxes helps you plan for future expenses, retirement needs, family support, and estate distribution.
Rather than making a large gift without considering your own financial security, you can assess how the transfer might affect your savings and long-term plans. Likewise, beneficiaries can prepare for the costs of maintaining, selling, or managing inherited assets.
In short, informed decisions help families balance generosity with financial responsibility.
Understanding the Difference Between Gift Tax and Inheritance Tax
Gift tax and inheritance-related taxes are often confused. However, they apply to different circumstances, and the distinction is especially important when planning a transfer of wealth.
| Tax or rule | What it generally concerns | Who may be responsible |
|---|---|---|
| Gift tax | Certain transfers made during the giver’s lifetime | The donor generally pays any federal gift tax due |
| Estate tax | The taxable transfer of a deceased person’s estate | The estate generally pays the tax |
| Inheritance tax | A tax on receiving an inheritance under certain jurisdictions | The beneficiary may be responsible |
| Income tax | Certain income received from inherited assets | The person or entity receiving taxable income |
| Capital gains tax | Profit from selling an asset | The person or entity that sells the asset |
In the United States, the federal government imposes gift and estate taxes under specific rules, but it does not impose a general federal inheritance tax. Some states, however, impose estate taxes, inheritance taxes, or both.
Additionally, a transfer may involve more than one tax consideration. An inheritance itself may not be taxable income to the beneficiary, for example, but income later generated by inherited assets may be taxable.
For that reason, it is important to identify the exact type of transfer rather than treating every gift or inheritance as the same transaction.
How Gift Tax Works When You Give Away Money
Gift tax is a federal tax system that applies to certain transfers of money or property made during a person’s lifetime without receiving something of equal value in return.
Nevertheless, not every gift creates a tax bill or even requires a gift tax return. Federal rules provide exclusions and deductions that may allow many transfers to take place without gift tax being owed.
Annual Gift Tax Exclusion
The annual exclusion allows a person to give up to a specified amount to each eligible recipient during a calendar year without using their lifetime gift and estate tax exemption, provided the gift meets the applicable requirements.
The exclusion is adjusted periodically for inflation. Therefore, you should verify the amount for the tax year in which the gift occurs instead of relying on an outdated figure.
For example, if a parent gives qualifying gifts to three different children, the annual exclusion generally applies separately to each child. As a result, the total amount the parent can give without using the lifetime exemption may be greater than the exclusion for one recipient.
Importantly, a gift above the annual exclusion does not automatically mean that gift tax must be paid. The donor may need to file a federal gift tax return, usually Form 709, and apply part of their available lifetime exemption.
Lifetime Gift and Estate Tax Exemption
The federal lifetime gift and estate tax exemption allows eligible transfers to exceed the annual exclusion without necessarily generating an immediate federal tax bill.
However, taxable gifts made during a person’s lifetime can reduce the exemption remaining for their estate. In addition, federal law determines the exemption amount and how it applies to lifetime gifts and transfers at death.
Therefore, someone planning substantial gifts should consider both their current transfer and their potential future estate.
Gifts That May Receive Special Treatment
Certain transfers may qualify for exclusions or deductions under federal law. For example, qualifying payments made directly to an eligible educational institution for tuition or directly to a medical provider for another person’s qualifying medical expenses may be excluded from gift tax.
Likewise, qualifying gifts to a spouse who is a U.S. citizen may receive special treatment under federal gift tax rules.
Nevertheless, the details matter. Payments for books, accommodation, medical insurance, or other expenses may not receive the same treatment as qualifying tuition or medical payments. Before relying on an exclusion, confirm that the transfer meets the exact legal requirements.
What Happens When You Receive an Inheritance?
Receiving an inheritance can provide financial security, but it is important to understand what happens after the assets are transferred.
In the United States, cash or property received as an inheritance generally is not included in the beneficiary’s federal gross income simply because they inherited it. However, that does not mean every financial benefit associated with an inheritance is tax-free.
For example, inherited assets may generate interest, dividends, rental income, or taxable retirement-account distributions. In addition, selling inherited property may create a capital gain or loss.
Inheriting Cash
Cash is generally the simplest type of inheritance to understand. If you receive money from a deceased relative’s estate, the inherited amount generally is not subject to federal income tax merely because you received it.
However, the estate may have tax obligations before the money is distributed. Depending on the circumstances, state inheritance tax rules may also apply.
Once the money belongs to you, any interest or investment income it generates may be taxable under the ordinary rules that apply to that income.
Inheriting a House or Other Property
Inherited real estate requires more careful planning because its tax treatment can depend on its value at the date of death, the deceased owner’s tax basis, and what the beneficiary does with the property.
Under general U.S. federal rules, inherited property often receives a tax basis equal to its fair market value at the owner’s date of death, subject to exceptions. Certain alternative valuation rules may apply in particular circumstances.
This treatment is commonly called a step-up in basis when the inherited property’s value has increased. It can reduce the capital gain that would otherwise arise if the beneficiary later sells the property.
For example, suppose a parent purchased a house for $150,000 and it was worth $400,000 when the parent died. If the beneficiary receives a $400,000 tax basis under the applicable rules and later sells the house for $420,000, the initial calculation may produce a $20,000 gain before selling costs and other adjustments.
The actual result depends on the circumstances, including the applicable basis rules and any subsequent improvements or other adjustments.
Inheriting Stocks and Investments
Inherited stocks, bonds, and other investments may also receive a basis adjustment under applicable federal rules.
Consequently, beneficiaries should obtain reliable valuation records for the date of death and keep documentation of later transactions. Without these records, calculating a gain or loss when selling investments may become more difficult.
Furthermore, dividends and interest received after the inheritance may be taxable even if the inherited investment itself was not treated as taxable income when received.
Inheriting Retirement Accounts
Retirement accounts can follow different rules from cash, real estate, and ordinary investment accounts.
For instance, distributions from inherited traditional individual retirement accounts (IRAs) are generally taxable to the beneficiary, except to the extent a distribution represents amounts that are not taxable under the applicable rules. Inherited Roth IRAs may receive different treatment, although distribution requirements can still apply.
Many non-spouse beneficiaries must empty inherited retirement accounts within a specified period, often 10 years, subject to exceptions. The exact requirements depend on the account type, the beneficiary’s relationship to the deceased, and other circumstances.
Therefore, beneficiaries should review distribution deadlines before withdrawing money. A poorly timed withdrawal can increase taxable income in a particular year or lead to avoidable penalties.
How Estate Tax Can Affect Your Family
Estate tax is another important consideration when transferring wealth after death. In the United States, federal estate tax generally applies to an estate’s taxable value when it exceeds the applicable exemption, after accounting for relevant deductions and adjustments.
However, most estates do not owe federal estate tax because the exemption is relatively high compared with the value of many estates. State estate taxes may apply at lower thresholds, depending on the jurisdiction.
Understanding the Federal Estate Tax Threshold
The federal estate tax exemption can change because of legislation and inflation adjustments. Therefore, people planning an estate should use the amount applicable to the year of death and consider the rules that apply to their circumstances.
A person’s taxable estate is not necessarily identical to the total value of everything they own. Deductions, qualifying transfers, debts, and other legal factors may affect the calculation.
As a result, the value of an estate alone does not always determine whether federal estate tax will be due.
Why Estate Planning Matters
Estate planning allows people to document how they want their assets distributed and identify potential tax issues before they become urgent.
For example, a person with a business, investment portfolio, real estate, or other substantial assets may need to coordinate beneficiary designations, ownership arrangements, and estate documents.
Additionally, careful planning can help reduce delays, avoid disputes, and provide clear instructions for executors and beneficiaries.
Nevertheless, tax reduction should not be the only objective. A sound plan should also reflect the person’s wishes, financial needs, family circumstances, and applicable legal requirements.
How Giving Money Away Can Affect Your Future Finances
Giving money to loved ones can be rewarding, but it is important to consider your own financial needs before making a substantial transfer.
For example, parents may want to help their adult children purchase a home, pay for college, or start a business. Although these gifts can provide valuable support, giving away too much too soon may reduce the money available for retirement, healthcare, emergencies, or other future expenses.
Balance Generosity With Financial Security
Before making a large gift, calculate how much you can comfortably afford to give. In addition, consider whether you might need those funds later.
A financial adviser can help you evaluate the effect of a transfer on your retirement plans, investment strategy, and emergency savings. This approach allows you to support loved ones without unnecessarily jeopardizing your own financial stability.
Understand the Difference Between Giving Cash and Giving Assets
Cash gifts are generally easier to value than gifts involving stocks, land, or real estate. However, transferring appreciated assets can create different tax consequences.
For example, when someone gives appreciated stock to another person, the recipient generally receives the donor’s existing tax basis rather than the date-of-transfer value. Consequently, the recipient may face a larger capital gain when selling the shares.
Inherited property, by contrast, often receives a different basis treatment. Therefore, comparing lifetime gifts with inheritances can be particularly important when transferring assets that have increased substantially in value.
Tax Implications of Giving Away Money or an Inheritance in 2026
Tax thresholds and reporting requirements can change over time. For U.S. readers, understanding the figures applicable in 2026 can make planning more practical.
| Federal tax rule | 2026 amount or treatment |
|---|---|
| Annual gift tax exclusion | $19,000 per recipient |
| Gifts from two spouses | Up to $38,000 per recipient under qualifying rules |
| Federal estate and gift tax basic exclusion | $15 million per individual, subject to applicable rules |
| Federal inheritance tax | No general federal inheritance tax |
| Gifts and inheritances received | Generally excluded from federal income, subject to exceptions |
The IRS confirms the 2026 annual gift exclusion of $19,000 per recipient and the $15 million basic exclusion amount.
These figures require careful interpretation. For example, the annual exclusion applies to qualifying gifts, and exceeding it may trigger a reporting requirement rather than an immediate tax bill. Similarly, the lifetime exemption applies under federal gift and estate tax rules, subject to the relevant calculations and adjustments.
Furthermore, state laws may impose additional taxes. Non-U.S. citizens, nonresident individuals, and people who own assets across borders may face different rules.
Therefore, verify the requirements for the specific year and jurisdiction before relying on any threshold.
Common Mistakes to Avoid When Giving Money or Receiving an Inheritance
Even a well-intentioned transfer can create unnecessary complications when people overlook tax requirements.
Assuming Every Large Gift Is Taxable
A common mistake is believing that every gift above the annual exclusion automatically results in tax.
In reality, the donor may need to file a gift tax return while using part of their lifetime exemption. Whether tax is actually due depends on the circumstances and the applicable rules.
Assuming Inheritances Are Always Tax-Free
Although inherited property generally is not federal taxable income when received, certain distributions and subsequent earnings can be taxable.
For instance, distributions from inherited traditional retirement accounts may be taxable, and profits from selling inherited property may trigger capital gains tax.
Forgetting to Keep Records
Another mistake is failing to document the amount, date, and nature of a gift or inherited asset.
Without accurate records, it can be difficult to establish the asset’s value, determine its tax basis, or prepare the correct return. Accordingly, keep transfer confirmations, appraisals, estate documents, and relevant tax forms.
Transferring Property Without Considering Its Tax Basis
Giving away an appreciated asset can affect the recipient’s future capital gains tax.
Before transferring stocks, a home, or other valuable property, compare the likely tax consequences of a lifetime gift with those of an inheritance. The best choice depends on ownership, future plans, and applicable tax rules.
Ignoring State and International Rules
Federal rules do not tell the whole story. Some states impose estate or inheritance taxes, while international transfers may involve additional reporting obligations.
Consequently, people with family members or assets in multiple countries should seek advice from someone familiar with the relevant jurisdictions.
How to Plan Gifts and Inheritances More Effectively
A few practical steps can make wealth transfers easier to manage.
- Review the rules first. Identify the applicable gift, estate, inheritance, and income tax requirements before making the transfer.
- Estimate the value of the assets. Obtain reliable valuations for real estate, investments, and other substantial property.
- Keep detailed records. Document the transfer date, recipient, amount, ownership, and relevant tax basis.
- Consider timing. Compare the consequences of giving assets during your lifetime with leaving them to beneficiaries through an estate.
- Review estate documents. Ensure your will, trust arrangements, and beneficiary designations reflect your current intentions.
- Consult qualified professionals. A tax professional or estate-planning attorney can identify issues that may not be obvious from general guidance.
- Protect your financial future. Make sure a gift does not compromise your own living expenses, retirement savings, or emergency reserves.
Above all, remember that tax planning should support your broader financial goals. The lowest possible tax bill is not necessarily the best outcome if the arrangement creates financial risk or fails to reflect your wishes.
Advantages and Disadvantages of Planning Gifts and Inheritances
Understanding the tax implications of wealth transfers has several benefits. However, planning can also involve costs, paperwork, and difficult decisions.
| Advantages | Disadvantages |
|---|---|
| Helps reduce avoidable tax mistakes | May require professional fees |
| Clarifies reporting obligations | Can involve detailed documentation |
| Supports informed financial decisions | Tax rules may change |
| Helps preserve family wealth | Some transfers are difficult to reverse |
| Reduces confusion among beneficiaries | Family discussions can be sensitive |
| Encourages organized estate planning | Complex estates may require substantial preparation |
Despite these challenges, careful planning can make wealth transfers more predictable and help families understand their responsibilities.
Gift vs. Inheritance: Which Is Better?
Neither giving money during your lifetime nor leaving it as an inheritance is automatically better. The appropriate option depends on your financial situation, the asset involved, and your family’s needs.
A lifetime gift may allow you to help a relative when they need financial support. For example, a parent might contribute toward a child’s home purchase or education expenses.
An inheritance, meanwhile, allows you to retain control of your assets during your lifetime. In addition, inherited property may receive a different tax basis from gifted property, potentially affecting future capital gains.
Before choosing, consider these factors:
- Your current financial needs and future retirement plans
- The recipient’s immediate financial circumstances
- Whether the transfer involves cash, real estate, investments, or retirement accounts
- Potential gift tax reporting requirements
- The tax basis of the property
- Applicable federal, state, and international rules
Ultimately, the right approach is the one that balances your goals, the recipient’s needs, and the legal and tax consequences.
Real-Life Examples of Gift and Inheritance Tax Planning
The following hypothetical examples illustrate why the details of a transfer matter.
Example: A Parent Gives Money to an Adult Child
Suppose a parent gives an adult child $25,000 in cash during 2026.
The annual federal gift tax exclusion is $19,000 per recipient. Assuming the entire gift qualifies for the exclusion and no other relevant gifts were made to that child during the year, the parent would generally need to report the $6,000 excess on a federal gift tax return.
However, that excess does not automatically mean the parent owes gift tax. The donor may apply the amount against the available lifetime gift and estate tax exemption.
Example: A Grandparent Pays College Tuition
Imagine a grandparent wants to help a grandchild pay for college.
If the grandparent pays qualifying tuition directly to the eligible educational institution, the payment may qualify for the federal educational gift tax exclusion. Nevertheless, money given directly to the student for general expenses does not automatically qualify for the same exclusion.
Therefore, the payment method can make a meaningful difference.
Example: A Beneficiary Inherits a House
Suppose someone inherits a house valued at $350,000 when the owner dies. Later, the beneficiary sells it for $365,000.
If the beneficiary receives a $350,000 tax basis under the applicable rules, the initial gain calculation would be $15,000 before eligible selling costs and other adjustments.
This example shows why retaining valuation records is important. The tax consequences of selling an inherited asset depend on its basis, the selling price, and applicable adjustments.
Example: A Beneficiary Inherits a Retirement Account
A person inherits a traditional IRA from a relative. Instead of checking the distribution rules, the beneficiary withdraws a substantial amount in one year.
Depending on the account and beneficiary’s circumstances, the distribution may be included in taxable income. Consequently, the withdrawal could increase the beneficiary’s tax bill for that year.
Reviewing the applicable distribution requirements and considering the timing of withdrawals may help the beneficiary plan more effectively.
Key Takeaway and Summary
Understanding the tax implications of giving away money or an inheritance helps people make informed decisions, protect family wealth, and avoid preventable financial surprises.
In the United States, gifts and inheritances generally are not taxable income to the recipient simply because they receive them. However, gift tax reporting, estate tax, state inheritance taxes, capital gains, and income from inherited retirement accounts can create separate obligations.
The most important points to remember are:
- Gift tax and estate tax are different from income tax.
- The donor generally handles federal gift tax responsibilities.
- The annual gift exclusion is $19,000 per recipient in 2026.
- The federal basic gift and estate tax exclusion is $15 million in 2026, subject to applicable rules.
- Inherited assets may have special tax-basis treatment.
- Income generated by inherited assets may be taxable.
- State and international rules can change the outcome.
- Accurate records and professional advice can help prevent costly mistakes.
In short, informed planning allows you to give generously, prepare beneficiaries, and transfer wealth with greater confidence.
Exercises With Answers
Test your understanding of gifts and inheritance taxes with these short questions.
Question: Does receiving a cash inheritance generally count as federal taxable income in the United States?
Answer: No. Cash received as an inheritance generally is not federal taxable income merely because it was inherited. However, other tax rules may apply to the estate or to income generated by the money.
Question: If a person gives a qualifying $25,000 cash gift to one recipient in 2026, what amount exceeds the $19,000 annual exclusion?
Answer: $6,000. The donor may need to report the gift, but the excess does not automatically create a gift tax bill.
Question: Who generally pays federal gift tax when it is due?
Answer: The donor, although special circumstances and exceptions may apply.
Question: Can selling an inherited house create capital gains tax?
Answer: Yes. If the sale produces a taxable gain after the applicable basis and adjustments are considered, capital gains tax may apply.
Question: Are all inherited retirement account distributions tax-free?
Answer: No. Distributions from inherited traditional retirement accounts are generally taxable to the extent provided by the applicable rules. Other account types may receive different treatment.
Frequently Asked Questions
Do I have to pay tax on money someone gives me?
In the United States, the recipient generally does not pay federal income tax simply because they receive a personal gift. However, the donor may have a gift tax reporting obligation, and special rules can apply to certain transfers.
How much money can I give someone tax-free in 2026?
The federal annual gift tax exclusion is $19,000 per recipient in 2026 for qualifying gifts. Gifts above that amount may require reporting, but they do not automatically result in tax being owed.
Do beneficiaries pay federal income tax on an inheritance?
Generally, no. The value of property received as an inheritance is usually excluded from federal gross income. Nevertheless, taxable income generated by inherited property and certain retirement account distributions may be subject to income tax.
Is inheritance tax the same as estate tax?
No. Estate tax generally applies to the taxable estate of a deceased person, while inheritance tax applies to the recipient in jurisdictions that impose it. The United States has a federal estate tax but no general federal inheritance tax.
Should I give my children money now or leave it to them in my will?
The answer depends on your financial needs, the type of asset, the recipient’s circumstances, and the tax rules. A lifetime gift may provide immediate support, while an inheritance may offer different tax-basis treatment and allow you to retain control of your assets during your lifetime.
Can I avoid all taxes by transferring property before I die?
Not necessarily. Lifetime transfers may trigger gift tax reporting, affect the recipient’s tax basis, or create other tax consequences. In addition, some transfers may be subject to special rules. Professional advice can help you evaluate the available options legally and accurately.
Should I consult a tax professional before giving away a large amount of money?
Yes, particularly when the transfer involves substantial wealth, appreciated property, business interests, trusts, retirement accounts, or assets in multiple jurisdictions. A qualified professional can explain reporting obligations and help you evaluate the potential consequences before you make a transfer.
Conclusion
Knowing the tax implications of giving away money or an inheritance is an important part of responsible financial planning. Although sharing wealth can support loved ones and preserve family legacies, the wrong assumptions about taxes can create unexpected expenses, reporting problems, or unnecessary complications.
Fortunately, understanding the difference between gifts, inheritances, estate taxes, income taxes, and capital gains gives you a stronger foundation for making informed decisions. By keeping accurate records, reviewing applicable rules, and seeking professional guidance when needed, you can make transfers with greater confidence.
Ultimately, thoughtful planning is about more than minimizing taxes. It helps you protect your financial security, respect your wishes, and ensure that the people you care about understand what to expect.